RBI Rate Hike Fear Drags Nifty Below 22,650 in Early Trade
Based on market data as of 10:05 IST on 07 October 2026.
At a glance
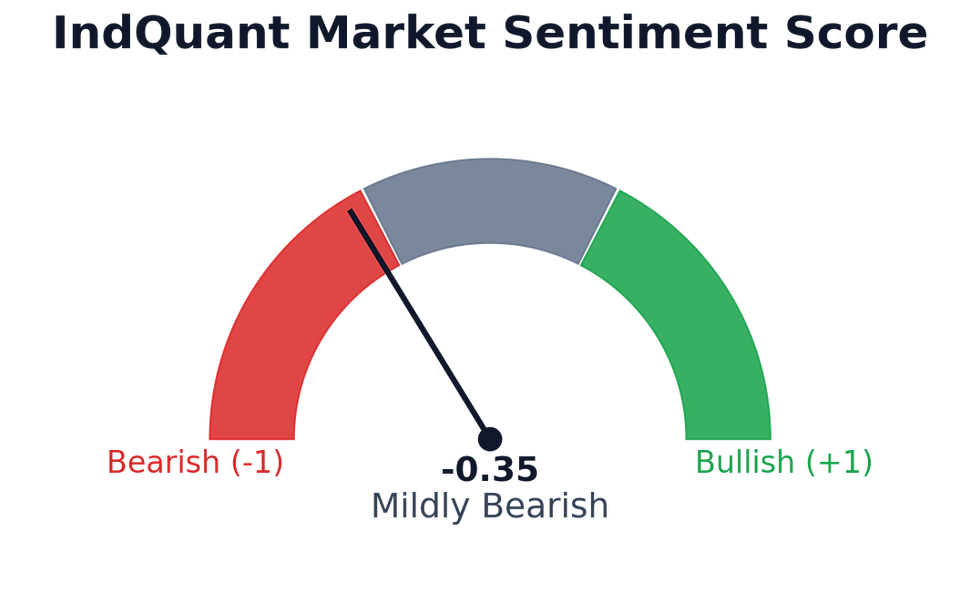
Sensex is down roughly 500 points and Nifty slipped below 22,650 in the first 45 minutes of trade, driven by expectations of a 25 basis point (bps) repo rate hike from the RBI (Reserve Bank of India) later today.
Brent crude has crossed $101 per barrel on Houthi shipping attacks and a US hurricane threat, squeezing India's import bill and adding to inflation worries.
Pharma is the lone bright spot in an otherwise red market, attracting defensive buying as investors rotate away from rate-sensitive sectors.
The setup
Forty-five minutes into the October 7 session, the direction is clear: sellers are in control. The Nifty 50 gapped down roughly 100 points at the open and has not recovered. The Sensex is nursing a loss of around 500 points. This is not a random sell-off — it has a single, dominant cause. The RBI's Monetary Policy Committee (MPC) is widely expected to announce a 25 bps hike in the repo rate (the rate at which the RBI lends money to commercial banks), taking it to 5.50%. This would be the first hike since February 2023, marking a clear shift away from the accommodative (growth-supportive, low-rate) policy stance India has held for over three years. Everything else happening in the market today — the weak rupee, the elevated crude price, the selling in financials — is amplifying that central fear.
Top 5 sentiment drivers
Macro risk factors. The RBI's expected 25 bps repo rate hike to 5.50% is the single biggest weight on the market right now, and it earns a strongly bearish score of -0.70. Layered on top are Brent crude above $101 per barrel, a rupee (INR) weakening to 96.45 per US dollar, and rising bond yields — together, these create a rare triple headwind of tighter money, costlier energy, and a weaker currency all hitting at once.
Banking sector outlook. The banking sector is bearing the brunt of rate-hike anxiety, scoring a bearish -0.60. Bank Nifty opened at 54,968.70, already down 0.29%, with SBI Life among the early decliners. The concern is straightforward: a rate hike can compress NIM (Net Interest Margin — the difference between what banks earn on loans and what they pay on deposits) and raise fears about credit costs, especially for PSU (Public Sector Undertaking) banks.
India regulatory stance. The RBI's policy decision is not just a rate number — it signals the end of an era of easy money, earning a bearish score of -0.55. Eight out of ten economists surveyed expect the hike, so the market is not caught off guard, but the confirmation will still matter. SEBI (Securities and Exchange Board of India), India's markets regulator, has not issued any new market-moving circulars today, so the regulatory spotlight remains firmly on the RBI.
Currency and commodity impact. The rupee opened 3 paise weaker at 96.45 per US dollar, and Brent crude is up 1.06% to $101.65 per barrel — together scoring a bearish -0.55. Houthi rebel attacks on Red Sea shipping lanes and a hurricane threatening US Gulf energy infrastructure are both pushing crude higher simultaneously. For India, which imports roughly 85% of its crude oil needs, every dollar added to the oil price widens the CAD (Current Account Deficit — the gap between what India earns from and pays to the rest of the world).
Market volatility outlook. India VIX (Volatility Index — a measure of how much the market expects prices to swing in the near term) is likely elevated, and the options market is already signalling caution, scoring a bearish -0.55. Put options (contracts that profit when prices fall) on the 22,650 Nifty strike are up 0.76%, showing active hedging. The Nifty carved out a single large red candle moving from 22,690 to 22,594 at the open — a sign that intraday swings could remain wide until the RBI announcement lands.

Sectors in focus
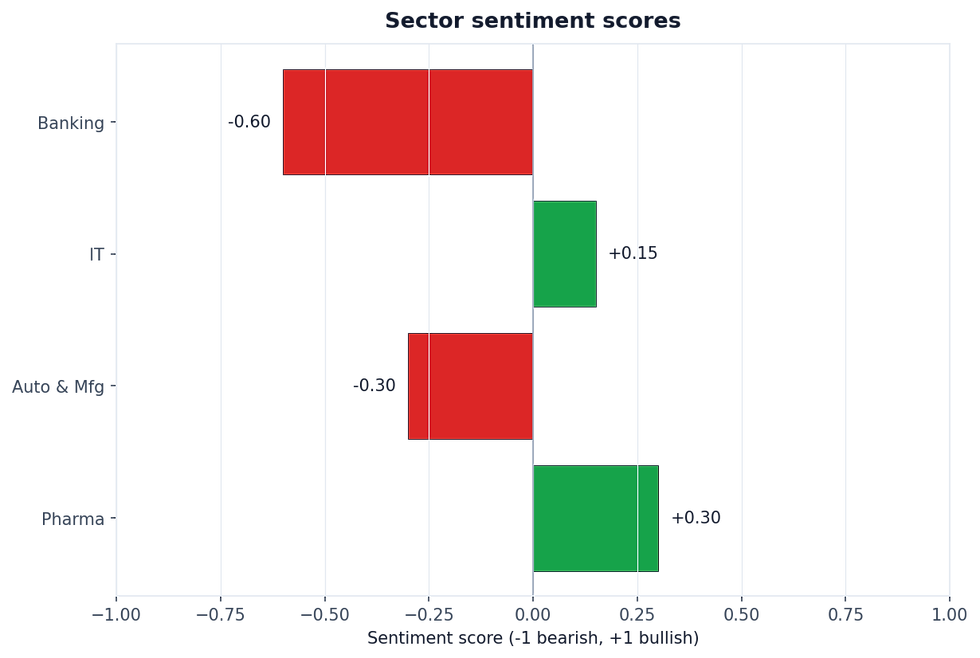
Banking. Bearish at -0.60 — Bank Nifty is down 0.29% at the open and rate-sensitive names like SBI Life are under pressure. A rate hike raises credit cost fears and limits NIM expansion hopes for both PSU and private banks, making this sector the most direct casualty of today's RBI anxiety.
IT. Mildly bullish at +0.15 — IT (Information Technology) is one of the quieter corners of the market today. TCS (Tata Consultancy Services) Q2 results are due soon, and brokerages are pencilling in healthy margin expansion, providing a mild positive undercurrent. IT stocks earn most of their revenue in US dollars, so they are relatively insulated from a domestic rate hike.
Auto and Manufacturing. Mildly bearish at -0.30 — No major company-specific data has emerged for auto names today, but the sector faces two structural headwinds: crude above $101 raises raw material and fuel costs, and a rate hike dampens consumer financing sentiment, making car loans more expensive. On the positive side, India's manufacturing exports — such as Crocs footwear production — are showing double-digit growth, offering a partial offset.
Pharma. Mildly bullish at +0.30 — Pharma is one of only two sectors (alongside Media) trading in the green at this hour, making it the clearest defensive play of the session. When rate-sensitive sectors sell off, investors often rotate into pharma because its earnings are less tied to interest rate cycles. No major USFDA (US Food and Drug Administration) actions on Indian companies have been flagged today.
Global and macro backdrop
Asian markets are sending mixed signals this morning. Japan's Nikkei fell 0.86%, weighed down by profit-booking in AI (Artificial Intelligence) stocks. Australia's ASX 200 slipped below 8,750, ending a three-session winning streak. Broader Asian indices were holding up slightly better, but none of this matters much today — the domestic RBI policy decision is completely overshadowing global cues.
On flows, no confirmed FII (Foreign Institutional Investor — large overseas funds investing in Indian markets) or DII (Domestic Institutional Investor — Indian mutual funds, insurance companies, etc.) data is available for this session yet. However, the combination of a weakening rupee and rising bond yields makes Indian equities less attractive to FIIs on a returns basis. When bond yields rise, fixed-income instruments become more competitive versus stocks, which can pull money away from equity markets. DIIs may provide some support, but rate-hike uncertainty limits their conviction in early trade.
The rupee at 96.45/USD and crude at $101.65/bbl are the two macro numbers every investor should watch through the rest of the session.
Risks to watch
RBI policy surprise: If the MPC hikes by more than 25 bps, or signals further hikes ahead in its policy statement, the sell-off could deepen sharply.
Crude escalation: Any fresh Houthi attack headline or hurricane landfall news could push Brent above $103–$104, adding another leg down to import-sensitive sectors.
Titan and earnings contagion: Titan's 4% crash on a Q2 earnings miss is a reminder that results season is live — any further misses from large-cap names could add to selling pressure.
Support levels breaking: Nifty is already testing support near 22,602. A clean break below this level could trigger stop-loss (automatic sell orders placed to limit losses) selling and accelerate the decline.
What this means for the rest of today's session
The next few hours will be defined by one event: the RBI's policy announcement. Until that lands, expect choppy, low-conviction trade with a bearish bias. Pharma and IT offer relative shelter, but broad indices are unlikely to recover meaningfully while rate uncertainty hangs over the market. Once the announcement is out, the market's reaction to the MPC's forward guidance — not just the rate number itself — will set the tone for the afternoon session and likely carry into tomorrow's open as well.
How to read this
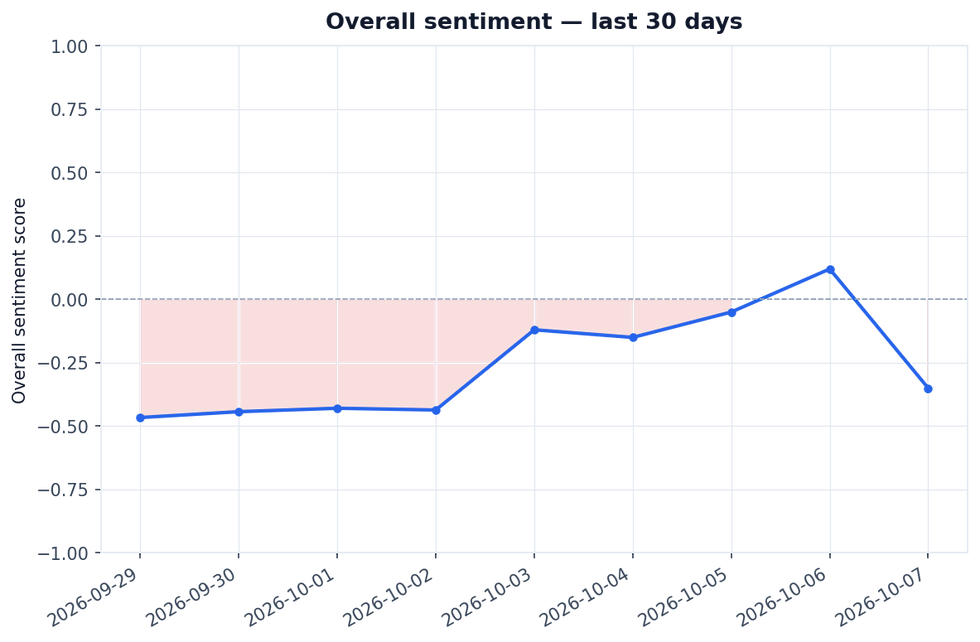
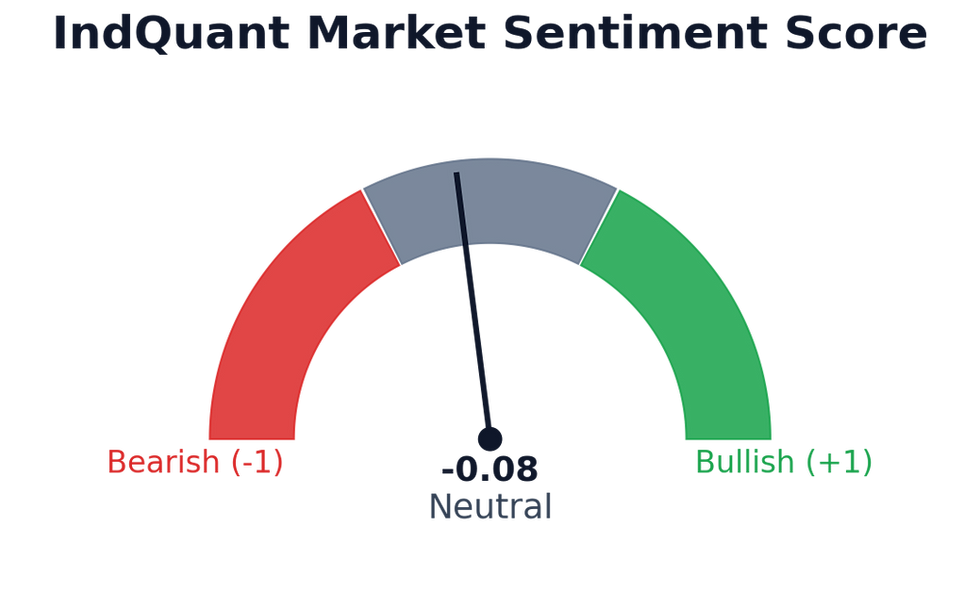
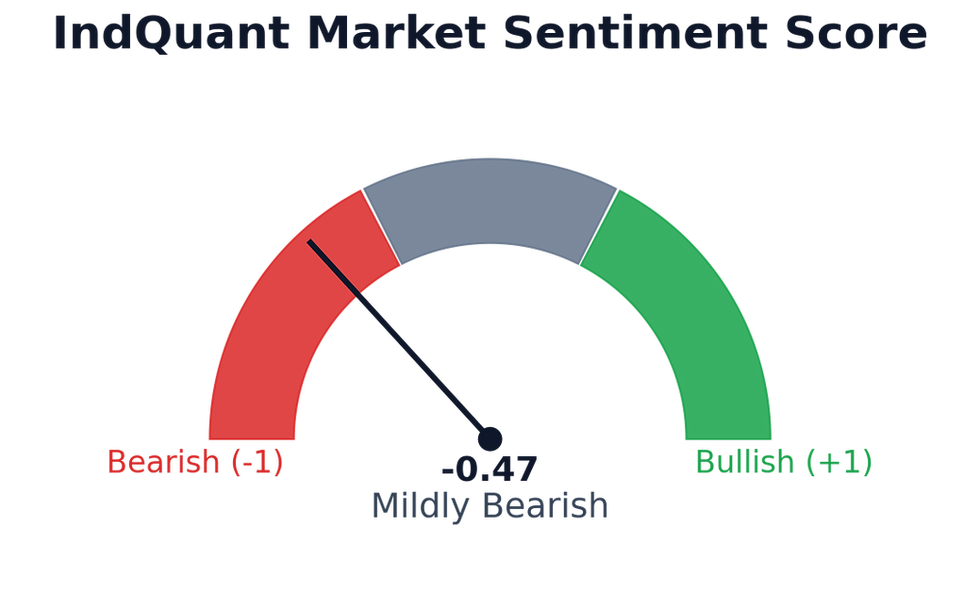
What this sentiment is measuring. We score 16 distinct dimensions of market sentiment, covering broad market direction, key sectors (banking, IT, auto and manufacturing, pharma), global cues, FII / DII flows, currency and commodities, regulatory stance across India and major foreign jurisdictions, and risk indicators. Each dimension is given a score from −1 (strongly bearish) to +1 (strongly bullish), paired with a 0 to 1 confidence weight that reflects how much supporting evidence the model found. The overall score shown in the dial is a confidence-weighted blend of all dimensions on the same −1 to +1 scale.
What data is used. The analysis draws on Indian and global financial news, regulatory and policy feeds from India as well as major foreign jurisdictions, and market news from global exchanges. News items are filtered for freshness and relevance before being scored, so the picture reflects what the market is reading and reacting to right now.
Limitations. This article is not investment advice and not a recommendation to buy, sell, or hold any security. The output is best treated as a structured attribute set — useful as one input among many when building your own prediction models or sense-checking your own view, not as a forecast on its own.
Comments