Nifty Bounces Above 22,350 But FII Selling Keeps the Rally on Thin Ice
Based on market data as of 10:05 IST on 09 October 2026.
At a glance
Sensex is up roughly 500 points and Nifty is holding above 22,350 in early trade, staging a technical relief bounce after Thursday's brutal 1,045-point crash.
TCS's Q2FY27 net profit jumped 14.9% year-on-year (YoY) to ₹13,884 crore (₹13,884 crore), lifting Nifty IT by 3.13% and carrying the broader market on its shoulders.
FII (Foreign Institutional Investor) outflows of $1.2 billion USD and crude oil above $100 per barrel are capping gains, with multiple analysts flagging sell-on-rally risk.
The setup
About 45 minutes into Friday's session, the market is doing exactly what a relief bounce looks like — up sharply from yesterday's lows, but not convincingly. The Nifty is sitting at 18-month lows and the Sensex at 32-month lows, so today's green numbers are coming off a very damaged base. One story is dominating the early tape: TCS's strong quarterly earnings are giving IT stocks a genuine fundamental reason to buy. Everything else — FII flows, crude, macro risks — is pointing the other way. The direction emerging right now is cautiously negative overall, with a single sector doing most of the work to keep the headline indices in the green.
Top 5 sentiment drivers
IT sector sentiment. TCS's Q2FY27 results are the engine of today's bounce — net profit up 14.9% YoY to ₹13,884 crore, a ₹12 interim dividend announced, and the stock trading 4–5% higher at around ₹2,149. Nifty IT has jumped 3.13% to 28,604, with Goldman Sachs and Nomura both putting out positive notes on the results. Management also dismissed concerns around the US PERM (Program Electronic Review Management — a US green card processing system) suspension, reaffirming a target of 15,000 US hires over five years. This driver is strongly bullish at +0.65.
FII/DII flow sentiment. FII (Foreign Institutional Investor) and FPI (Foreign Portfolio Investor — overseas funds that buy Indian stocks and bonds) outflows are the single biggest headwind right now. A sudden $1.2 billion USD outflow from Indian markets has been reported, and analysts are directly attributing Thursday's 1,045-point Sensex crash to this institutional selling wave. That single session wiped out roughly ₹10 lakh crore (₹10,00,000 crore) in market capitalisation. DII (Domestic Institutional Investor — mutual funds, insurance companies, etc.) buying data is not yet available to confirm whether domestic money is stepping in to absorb the pressure. This driver is moderately bearish at -0.55.
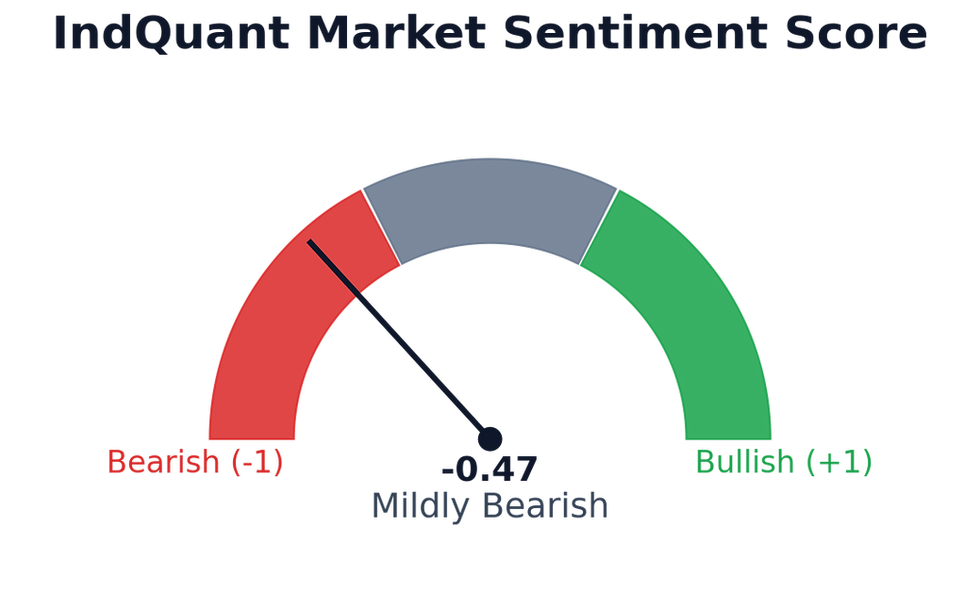
Risk factors. The structural picture is uncomfortable. Nifty is at an 18-month low and Sensex at a 32-month low — these are not short-term wobbles. Crude oil is above $100 per barrel (Brent at roughly $102.93), which raises India's CAD (Current Account Deficit — the gap between what India imports and exports) and keeps inflation elevated. The Firmus IPO withdrawal globally signals a broader risk-off mood among investors. Multiple analysts have explicitly flagged sell-on-rally dynamics, meaning any bounce could attract fresh selling. This driver is moderately bearish at -0.45.
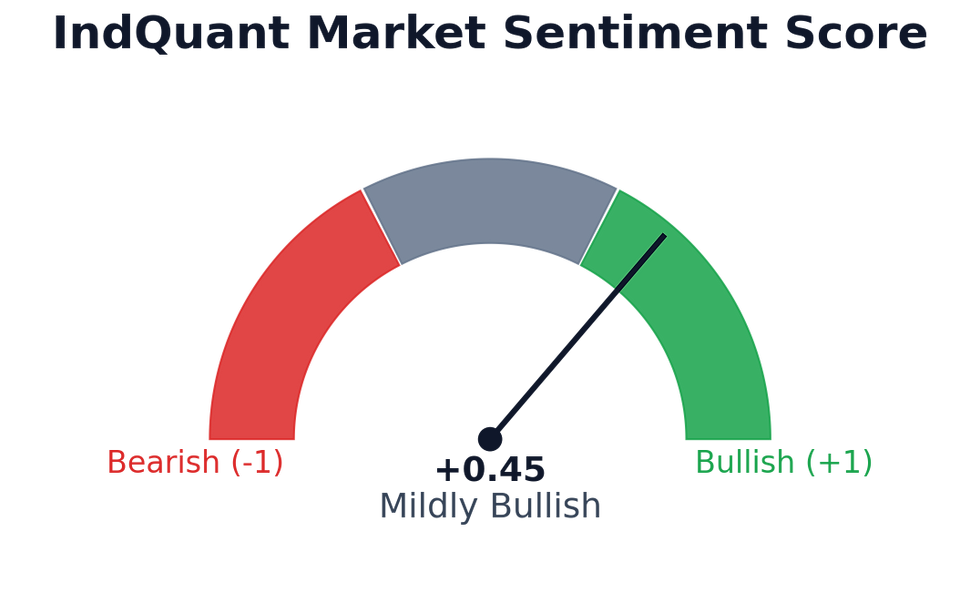
Stocks to watch. Beyond TCS, there are a few individual bright spots in early trade. KEC International has surged 5% after winning a ₹1,030 crore (₹1,030 crore) order, which is notable given the stock is down 51% year-to-date (YTD). Diamond Power Infrastructure is trading above its VWAP (Volume-Weighted Average Price — the average price weighted by trading volume, used as an intraday benchmark). Poonawalla Fincorp and Dr. Reddy's have Q2 results pending today, which could move those names later in the session. This driver is mildly bullish at +0.45.
Key corporate narratives. TCS dominates the corporate story today, but it is not the only one. KEC International's order win adds a positive note for the capital goods space. On the negative side, FSSAI (Food Safety and Standards Authority of India) has issued notices to Dr. Reddy's and Nestle Health Science over misleading advertising claims, creating a regulatory overhang for those names specifically. The Elon Musk versus Mukesh Ambani Starlink dispute is also simmering in the background as a watch item for telecom and satellite internet policy. This driver is mildly bullish at +0.40.

Sectors in focus
Banking. Mildly bearish at -0.30 — FPI outflows of $1.2 billion USD tend to hit large-cap banking stocks hardest, as they are the most liquid and easiest for foreign funds to sell. Elevated crude at $102.93/bbl keeps the inflation and interest rate outlook uncertain, which is not helpful for bank margins. Poonawalla Fincorp's Q2 results due today could provide a small catalyst, but the broader sector lacks a positive trigger right now.
IT. Strongly bullish at +0.65 — this is the only sector firing on all cylinders in early trade. TCS's earnings beat has given the entire IT index a lift, with Nifty IT up 3.13%. The US PERM suspension risk appears contained for now based on management commentary, and both Goldman Sachs and Nomura have added institutional credibility to the post-results rally.
Auto and Manufacturing. Mildly bullish at +0.20, though with low confidence. KEC International's 5% jump on a fresh ₹1,030 crore order is the standout move in manufacturing. However, crude above $100/bbl is a direct input cost pressure for auto companies, and there is no fresh news on Maruti, Tata Motors, or M&M in early trade. China's NDRC (National Development and Reform Commission) plan to boost domestic consumption could indirectly benefit Indian auto component exporters, but that is a slow-burn theme.
Pharma. Mildly bearish at -0.15 — FSSAI notices to Dr. Reddy's and Nestle Health Science are the headline risk here. There are no fresh USFDA (US Food and Drug Administration) approvals or positive drug pipeline announcements to offset the regulatory noise. The broader market weakness at multi-year lows is also weighing on pharma valuations in early trade.

Global and macro backdrop
The global backdrop is mixed but leaning cautious. On the positive side, US President Trump has ruled out Iran strikes, which caused Brent crude to fall 1.29% — though at $102.93/bbl it remains well above $100, meaning the geopolitical risk premium has only partially unwound. US jobless claims came in at 197,000, below expectations, which keeps the US Federal Reserve's rate-cut path uncertain. Fewer Fed rate cuts generally mean a stronger US dollar and continued pressure on emerging market (EM) capital flows — including India. The rupee and broader currency picture is relatively stable for now, but FII outflows of this magnitude ($1.2 billion in a single session) are a serious stress signal. DII flow data for today has not yet been confirmed, making it difficult to assess whether domestic institutions are providing a floor.
Risks to watch
Sell-on-rally dynamics: Multiple analysts have flagged this explicitly — any bounce from Thursday's crash could attract fresh FII selling, especially with Nifty at 18-month lows.
Crude oil staying above $100/bbl: Every day crude holds above this level, India's import bill grows and the CAD widens, adding pressure on the rupee and inflation.
US PERM suspension: TCS management has dismissed the impact, but if other large IT firms flag workforce concerns in their upcoming results, sentiment could shift quickly.
Pending Q2 results: Poonawalla Fincorp and Dr. Reddy's report today — a miss from either could add intraday selling pressure in financials and pharma respectively.
What this means for the rest of today's session
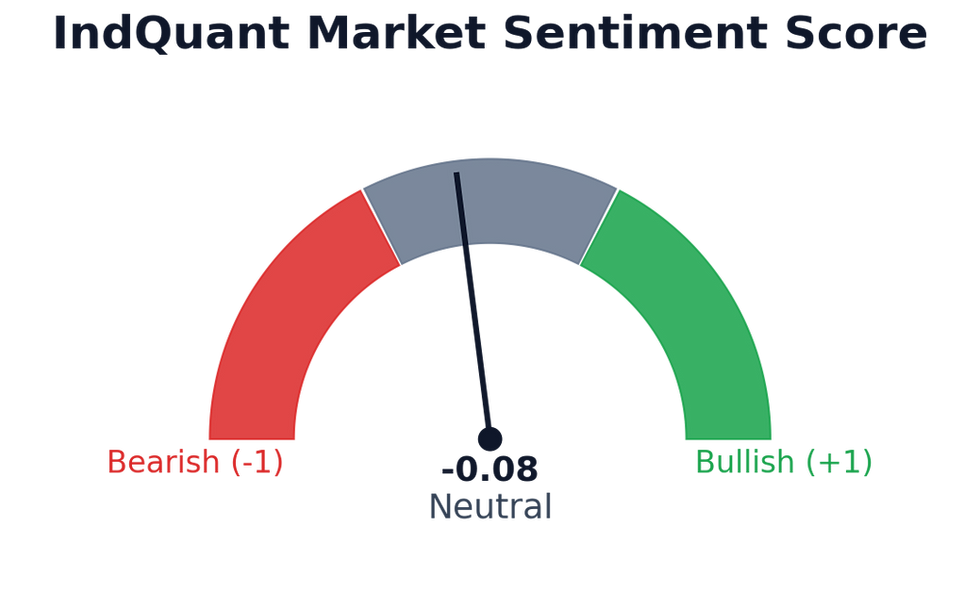
The next few hours will test whether TCS's earnings can sustain the IT-led bounce or whether FII selling pressure reasserts itself across banking and broader indices. The overall sentiment score of -0.08 — nearly flat but slightly negative — captures this tug-of-war precisely. Readers should watch the Nifty IT index for signs of profit-booking after the sharp morning gap-up, and keep an eye on Bank Nifty as a gauge of whether FII outflows are continuing. A close above 22,350 on Nifty would be a small technical positive heading into the long weekend, with the next trading day being Monday, 12 October.

How to read this
What this sentiment is measuring. We score 16 distinct dimensions of market sentiment, covering broad market direction, key sectors (banking, IT, auto and manufacturing, pharma), global cues, FII / DII flows, currency and commodities, regulatory stance across India and major foreign jurisdictions, and risk indicators. Each dimension is given a score from −1 (strongly bearish) to +1 (strongly bullish), paired with a 0 to 1 confidence weight that reflects how much supporting evidence the model found. The overall score shown in the dial is a confidence-weighted blend of all dimensions on the same −1 to +1 scale.
What data is used. The analysis draws on Indian and global financial news, regulatory and policy feeds from India as well as major foreign jurisdictions, and market news from global exchanges. News items are filtered for freshness and relevance before being scored, so the picture reflects what the market is reading and reacting to right now.
Limitations. This article is not investment advice and not a recommendation to buy, sell, or hold any security. The output is best treated as a structured attribute set — useful as one input among many when building your own prediction models or sense-checking your own view, not as a forecast on its own.

Comments