Nifty Holds 22,500 at Midday: TCS Earnings and Crude Relief Drive Rebound
Based on market data as of 13:05 IST on 09 October 2026.
At a glance
Sensex is up roughly 800 points and Nifty has crossed 22,500, with the morning rally holding into the lunch hour.
TCS (Tata Consultancy Services) reported a 14.9% year-on-year rise in Q2FY27 net profit to ₹13,884 crore (₹13,884 crore), pulling Nifty IT up over 3%.
Despite today's strength, Nifty risks a ninth consecutive weekly loss — a structural concern that keeps the overall mood cautiously bullish rather than euphoric.
The setup
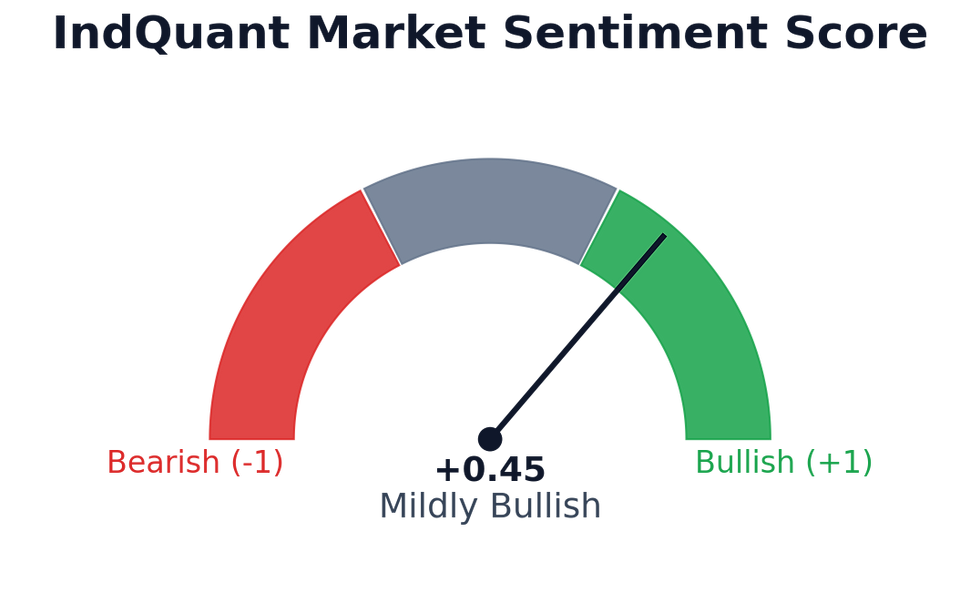
At 1:05 PM IST, Indian markets are roughly at the midpoint of the session, and the morning trend has largely held. The opening gap-up — triggered by TCS's strong quarterly results and a geopolitical risk release after US President Trump ruled out Iran strikes before the midterm elections — has not faded into profit-booking as some traders feared. Instead, the Sensex is consolidating near its highs. The overall sentiment score sits at a moderate +0.45 out of +1.0, which captures the mood well: this is a genuine rally, but not one without caveats. With about 2.5 hours left in the session, the question is whether buyers can sustain this momentum into the close — or whether rising US Treasury yields and technical resistance near 22,530 on the Nifty will cap gains.
Top 5 sentiment drivers
IT sector sentiment. TCS's Q2FY27 net profit of ₹13,884 crore, up 14.9% year-on-year, combined with an ₹12 per share interim dividend, sent the stock up 4–6% and lifted the Nifty IT index over 3% — making this the single strongest driver of today's session, strongly bullish at +0.70. Analysts at Goldman Sachs and Nomura weighed in post-results, though margin weakness and the sector's fourth consecutive year of subdued growth due to AI disruption and geopolitical headwinds remain concerns that temper the celebration.
Key corporate narratives. Beyond TCS, the corporate story is broadly constructive, scoring a solidly bullish +0.65. Reliance Industries' O2C (Oil-to-Chemicals) segment earnings are projected to rise 38% to ₹20,700 crore, partly aided by a European diesel shortage. Hospital stocks — Apollo Hospitals, Max Health, Fortis Healthcare, and Medanta — surged up to 5% after the government capped cancer drug trade margins at 30%, a policy move that could save patients ₹2,500 crore annually. The Fusion CX IPO (Initial Public Offering) is priced at ₹275–289 per share, adding primary market activity to the mix.
Stocks to watch. Individual stock moves are amplifying the broader rally, contributing a bullish +0.60 to sentiment. TCS is the headline name, up 4–5.6%, but Wipro, HCL Technologies, and Infosys are all rising in sympathy. Apollo Hospitals and Max Health are the standout healthcare plays on the drug price cap. Cupid Ltd hit a 52-week high with a 3% gain today — the stock has delivered a staggering 15,410% return over five years. On the cautious side, Anand Rathi Wealth fell 3.67% ahead of its Q2 results, a reminder that pre-earnings positioning can cut both ways.
Earnings momentum and corporate health. The Q2FY27 earnings season has opened on a positive note, earning a bullish +0.60 score. TCS has set a constructive tone, and Reliance's projected O2C numbers add to the optimism. However, the pipeline matters as much as the opener: HCL Technologies and Tech Mahindra are yet to report, and their results will provide a fuller read-through on whether the IT sector's recovery is broad-based or concentrated in TCS alone. Margin pressure flagged by analysts at TCS is a detail worth watching as more results come in.
Pharma and healthcare sentiment. The government's decision to cap cancer drug trade margins at 30% is a clear policy positive for hospital operators, pushing this sector to a bullish +0.60 score. Apollo Hospitals, Max Health, Fortis Healthcare, and Medanta all gained up to 5% on the news. Jefferies maintained its bullish stance on the hospital sector following the cap announcement. Crucially, there are no adverse USFDA (US Food and Drug Administration) actions in today's session — a clean slate that removes a common source of downside surprise for Indian pharma stocks.

Sectors in focus
Banking. Mildly bullish at +0.55 — HDFC Bank, SBI (State Bank of India), Federal Bank, and Canara Bank are each up approximately 2%, riding the broader market rebound and positive analyst commentary on bank balance sheet quality. The key risk hanging over the sector is the surge in US Treasury yields, which tightens global lending conditions and could pressure foreign capital flows into Indian banks.
IT. Strongly bullish at +0.70 — this is today's lead sector, and TCS is the engine. The Nifty IT index is up over 3%, with peer stocks rising in sympathy ahead of their own results. The structural caveat — India IT facing its fourth consecutive year of weak growth due to AI-led disruption and global spending caution — means today's move is a results-driven bounce rather than a sector re-rating.
Auto & Manufacturing. Mildly bullish at +0.30, though with low confidence given limited direct data from today's session. Easing crude oil prices are a genuine positive for auto sector margins. KEC International has been flagged as a top pick by brokerages, and Bonfiglioli's planned ₹2,500 crore IPO — with its India arm contributing 31% of group EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortisation) — signals strong manufacturing capex confidence. No major news on Maruti, Tata Motors, or M&M today.
Pharma. Bullish at +0.60 — the cancer drug margin cap is the catalyst, and hospital stocks have responded sharply. The absence of any negative USFDA news keeps the broader pharma space calm. Jefferies' continued bullish stance on hospitals adds institutional weight to the move.

Global and macro backdrop
Global cues are mixed-to-positive. Trump's statement ruling out Iran strikes before the US midterm elections was the key geopolitical trigger, sparking a risk-on open in European markets and easing crude oil prices — both directly beneficial for India's Current Account Deficit (CAD), which is sensitive to oil import costs.
The Indian Rupee appreciated 23 paise to 96.65 against the US Dollar, supported by a softening Dollar Index (DXY). A stronger Rupee reduces the cost of India's dollar-denominated imports and can attract FPI (Foreign Portfolio Investor) inflows. Gold rose ₹1,500 per 10 grams and silver gained ₹3,100 per kilogram, reflecting softer US yields at the margin.
On the flow side, direct FII (Foreign Institutional Investor) and DII (Domestic Institutional Investor) data for today's session is not yet confirmed, but the pattern of recent weeks — sustained FII selling contributing to Nifty's potential ninth consecutive weekly loss — suggests that today's rebound is likely being supported by DII buying and short-covering rather than a fresh wave of foreign inflows. The Rupee's appreciation to 96.65 does hint at some capital inflow activity. Singapore's central bank (MAS — Monetary Authority of Singapore) is expected to tighten monetary policy on October 14, which adds a near-term EM (Emerging Market) pressure point to monitor.
Risks to watch
Technical resistance at 22,530: Options market data points to caution at this level on the Nifty. A failure to close above it could set up a weak Friday finish and cement the ninth consecutive weekly loss.
Rising US Treasury yields: Surging yields tighten global financial conditions, pressure bank earnings worldwide, and historically trigger FII outflows from emerging markets like India.
Iran risk is eased, not eliminated: Trump's statement reduces the immediate risk premium, but the threat is described as latent post-midterms — crude oil could reprice quickly if the situation changes.
HCL Tech and Tech Mahindra results: If these upcoming IT results disappoint on margins or revenue growth, the sympathy rally in Nifty IT could partially unwind before the close or early next week.
What this means for the rest of today's session
The next 2.5 hours will test whether today's rally has genuine depth or is a relief bounce running out of fuel. The Nifty holding above 22,500 into the close would be a meaningful signal — it would reduce (though not eliminate) the risk of a ninth consecutive weekly loss heading into the weekend. Watch the IT sector closely: any brokerage commentary on TCS margins or early whispers about HCL Tech's results could move the index in either direction. Broader market breadth and whether banking stocks can extend their 2% gains will be the secondary indicator. The session is constructive, but the closing bell, not the lunchtime reading, will tell the real story.

How to read this
What this sentiment is measuring. We score 16 distinct dimensions of market sentiment, covering broad market direction, key sectors (banking, IT, auto and manufacturing, pharma), global cues, FII / DII flows, currency and commodities, regulatory stance across India and major foreign jurisdictions, and risk indicators. Each dimension is given a score from −1 (strongly bearish) to +1 (strongly bullish), paired with a 0 to 1 confidence weight that reflects how much supporting evidence the model found. The overall score shown in the dial is a confidence-weighted blend of all dimensions on the same −1 to +1 scale.
What data is used. The analysis draws on Indian and global financial news, regulatory and policy feeds from India as well as major foreign jurisdictions, and market news from global exchanges. News items are filtered for freshness and relevance before being scored, so the picture reflects what the market is reading and reacting to right now.
Limitations. This article is not investment advice and not a recommendation to buy, sell, or hold any security. The output is best treated as a structured attribute set — useful as one input among many when building your own prediction models or sense-checking your own view, not as a forecast on its own.

Comments