Sensex Up 600 Points at 10 AM: Banking Leads, Geopolitics Caps the Rally
Based on market data as of 10:05 IST on 05 October 2026.
At a glance
Sensex is trading near 72,540 and Nifty above 22,550 as of 10:05 IST, up roughly 600 points from Friday's close, snapping an eight-consecutive-week losing streak.
Banking and financials are the clear early leaders, powered by the HDFC Bank CEO appointment and Yes Bank's strong Q2 FY27 (April–September 2026) results; metals are also gaining.
Geopolitical risk — Middle East tensions and elevated crude oil prices — remains the key ceiling on how far this rally can run today.

The setup
About 45 minutes into Monday's session, the direction is unmistakably bullish, but measured. The Sensex opened roughly 413 points higher and has extended those gains to around 600 points, with broad participation from banking, metals, and select IT names. This is not a narrow, speculative move — it is being driven by concrete domestic catalysts: a leadership resolution at India's largest private bank and a strong early earnings signal from Yes Bank. Yesterday's themes of caution around geopolitics have not disappeared, but they are, for now, taking a back seat to positive domestic news flow. The overall sentiment score sits at a moderately bullish +0.38, which tells you the market is optimistic but not euphoric.
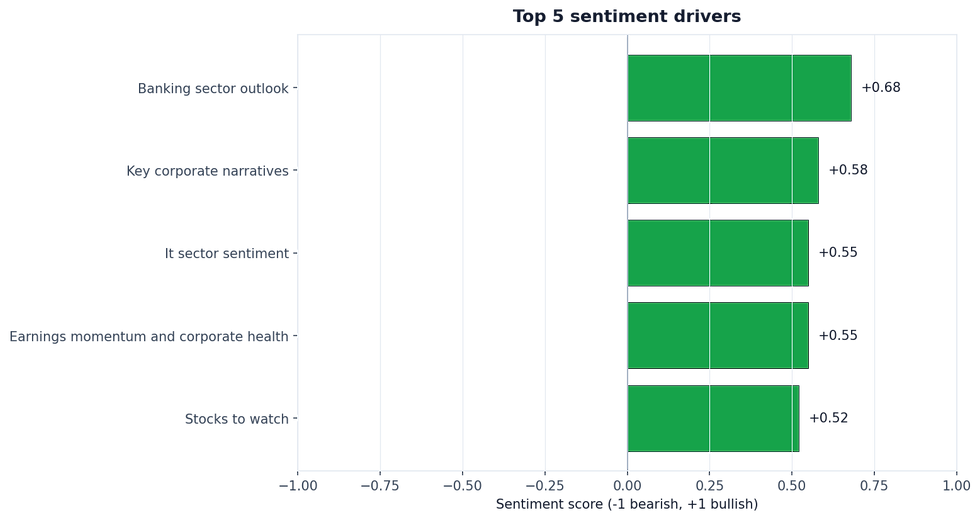
Top 5 sentiment drivers
Banking sector outlook. HDFC Bank (India's largest private sector lender by assets) jumped 2% after Anup Bagchi was named CEO, resolving a leadership vacuum that had weighed on the stock through a 25% decline over the past year; Yes Bank surged 3% on Q2 FY27 loan growth of 23.8% year-on-year (YoY) to ₹3.1 lakh crore (₹3,10,000 crore), with deposits up 20% YoY; PSU (Public Sector Undertaking) banks are also leading index gains — making banking the strongest single driver of today's session, strongly bullish at +0.68.
Key corporate narratives. Beyond banking, the early corporate story is broadly positive — Marico has guided for double-digit Q2 revenue growth on domestic demand, and the German Green Steel IPO (Initial Public Offering) has listed after a 30.42x subscription with a 7% GMP (Grey Market Premium, an unofficial indicator of listing demand); the one sharp negative is V2 Retail, down 19% on weak same-store sales, a reminder that consumption is not uniformly strong; this driver reads as moderately bullish at +0.58.
IT sector sentiment. Accenture's upbeat business forecast — released last week — is providing a positive read-through for Indian IT (Information Technology) companies, lifting the Nifty IT index in early trade; softer US inflation data has also reduced fears of another US Federal Reserve (Fed) rate hike in October, which supports tech stock valuations globally; that said, IT is lagging financials and metals in today's session, making it a secondary rather than a leading driver — moderately bullish at +0.55.
Earnings momentum and corporate health. The Q2 FY27 earnings season is only just beginning, but the early signals are constructive: Yes Bank's credit growth, Marico's revenue guidance, and HDFC Bank's positive Q2 business update all point to a healthier corporate earnings cycle than the market had feared; the outlier is V2 Retail, where 28.4% revenue growth still produced weak margins and same-store sales — a margin-quality concern worth monitoring as more results arrive; this driver is moderately bullish at +0.55.
Stocks to watch. The individual stock moves today are telling a clear story — HDFC Bank and Yes Bank are the momentum names on the upside, while V2 Retail's 19% plunge and Bajaj Finance's continued year-to-date (YTD) pressure from equity dilution concerns show that not every financial name is benefiting equally; German Green Steel's listing and Runwal Enterprises' flat debut at ₹305 round out the IPO watch; the aggregate read here is moderately bullish at +0.52.
Sectors in focus
Banking. Strongly bullish at +0.68 — HDFC Bank's CEO clarity and Yes Bank's loan growth numbers have made financials the undisputed leader of this session, with PSU banks adding breadth to the rally; the one note of caution is Bajaj Finance, which is down 4% YTD on equity dilution concerns, showing that stock selection within the sector still matters.
IT. Moderately bullish at +0.55 — the Accenture tailwind and reduced Fed rate hike fears are real positives for Indian IT exporters, but the sector is visibly underperforming banking and metals in early trade; investors appear to be rotating into higher-beta domestic plays first, treating IT as a steady rather than exciting position today.
Auto and Manufacturing. Mildly bullish at +0.38 — there is no direct auto-company data moving the needle this morning, but metals leading the broader market signals positive manufacturing sentiment; the government's push to build domestic rare-earth magnet capacity (relevant for EV supply chains) is a medium-term positive flagged by former RBI (Reserve Bank of India) Governor Shaktikanta Das.
Pharma and Healthcare. Mildly bearish at -0.10 — healthcare is the one sector BusinessLine flagged as a relative drag on the market this morning; there are no USFDA (US Food and Drug Administration) approvals or rejections in today's news flow, and while the Russia plague-lab incident (a researcher death with roughly 200 people quarantined) could eventually boost bio-defence pharma sentiment, that is speculative at this stage.

Global and macro backdrop
Global cues are broadly supportive this morning. Softer-than-expected US inflation data released late last week has reduced the probability of an October Fed rate hike, which is positive for emerging market (EM) capital flows — including India. Gold prices rose on the back of this data, signalling that global investors are moving toward risk assets. Accenture's positive business outlook has lifted NASDAQ sentiment, providing a tailwind for Indian IT. On flows, there is no direct FII (Foreign Institutional Investor) or DII (Domestic Institutional Investor) data available yet for today's session, but the eight-week losing streak being snapped suggests either reduced FII selling pressure or active DII absorption — PSU bank and metals leadership is consistent with DII-driven buying patterns. The rupee (INR) is likely to find some support from a softer US dollar, though elevated crude oil prices remain a fiscal concern — India imports roughly 85% of its crude needs, so every sustained rise in Brent directly pressures the current account deficit and government finances.
Risks to watch
Crude oil and Middle East tensions: Ongoing conflict in the Middle East keeps an upward risk premium on crude prices, which is a direct headwind for India's import bill and inflation.
Russia bio-risk: A plague-lab researcher death with approximately 200 people quarantined is an early-stage story, but any escalation could inject fresh risk-off sentiment into global markets.
Earnings quality vs. growth: V2 Retail's 19% drop despite 28.4% revenue growth is a warning that top-line numbers alone will not satisfy the market this earnings season — margins and same-store metrics will be scrutinised.
Bajaj Finance equity dilution: Continued pressure on Bajaj Finance (down 4% YTD) could act as a drag on the broader NBFC (Non-Banking Financial Company) space if dilution concerns are not addressed.
What this means for the rest of today's session
The early momentum is real and broad-based enough to suggest the gains can hold through the session, provided no fresh geopolitical shock emerges. Banking will likely remain the anchor — watch whether HDFC Bank and Yes Bank can sustain their opening moves, as any fade there would quickly take the index with it. The key question for the afternoon is whether FII flows turn net positive, which would confirm that this is a genuine trend reversal rather than a one-day bounce after eight weeks of selling. For now, the market is telling a cautiously optimistic story, and the data supports it.

How to read this
What this sentiment is measuring. We score 16 distinct dimensions of market sentiment, covering broad market direction, key sectors (banking, IT, auto and manufacturing, pharma), global cues, FII / DII flows, currency and commodities, regulatory stance across India and major foreign jurisdictions, and risk indicators. Each dimension is given a score from −1 (strongly bearish) to +1 (strongly bullish), paired with a 0 to 1 confidence weight that reflects how much supporting evidence the model found. The overall score shown in the dial is a confidence-weighted blend of all dimensions on the same −1 to +1 scale.
What data is used. The analysis draws on Indian and global financial news, regulatory and policy feeds from India as well as major foreign jurisdictions, and market news from global exchanges. News items are filtered for freshness and relevance before being scored, so the picture reflects what the market is reading and reacting to right now.
Limitations. This article is not investment advice and not a recommendation to buy, sell, or hold any security. The output is best treated as a structured attribute set — useful as one input among many when building your own prediction models or sense-checking your own view, not as a forecast on its own.


Comments