RBI's Surprise Hike Rattles Markets at Midday — But Earnings Fight Back
Based on market data as of 13:05 IST on 07 October 2026.
At a glance
Sensex is down 529 points and Nifty has shed 191 points as the RBI's (Reserve Bank of India's) first rate hike in four years — 25 basis points to 5.50% — dominates sentiment at the halfway mark.
A projected 27% year-on-year Nifty 50 earnings growth for Q2, a 17-quarter high, is the main counterweight keeping the sell-off from deepening further.
FOMC (Federal Open Market Committee) minutes are due later today; combined with Brent crude at $105 per barrel and the rupee at 96.45 per US dollar, the final 2.5 hours carry meaningful volatility risk.

The setup
Indian markets opened under pressure this morning and, as of 1:05 PM IST, the sell-off has stabilised rather than accelerated — a small but meaningful distinction. The RBI's decision to hike the repo rate (the rate at which the RBI lends to commercial banks) by 25 basis points to 5.50%, its first hike in four years, was the morning's defining shock. Governor Sanjay Malhotra's explicit signal that no rate cuts are on the horizon added a hawkish sting. Yet the market has not collapsed further from its morning lows, partly because Q2 earnings data flowing in is genuinely strong. The question for the afternoon session is whether that earnings cushion holds as FOMC minutes and crude oil headlines compete for attention.
Top 5 sentiment drivers
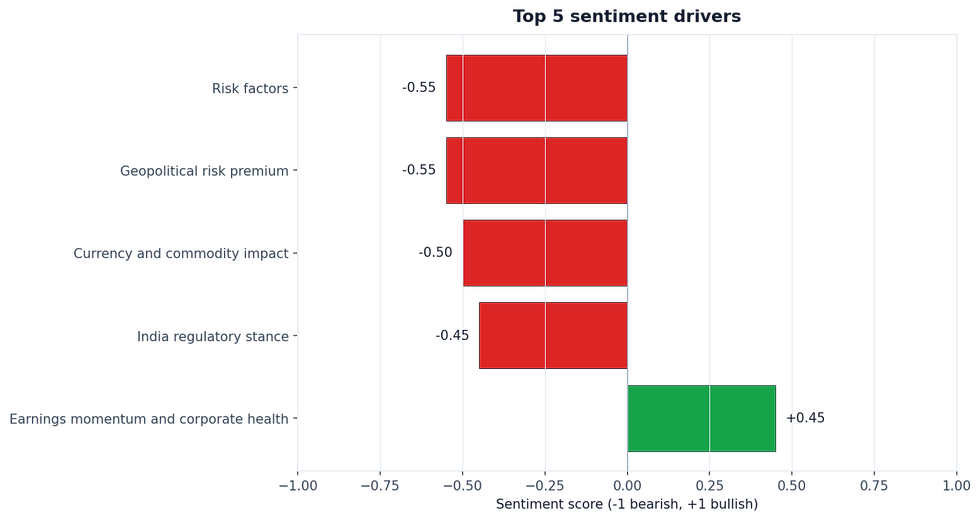
Risk factors. The RBI's hawkish pivot — a 25 bps hike to 5.50% with forward guidance ruling out cuts — sits at the centre of today's risk picture, and the score reflects it: strongly bearish at -0.55. Add a rupee at 96.45/USD, Brent crude forecast at $105/barrel, and FOMC minutes still pending, and the risk stack is unusually crowded for a single session.
Geopolitical risk premium. The Iran war continues to tighten global oil supply, with the EIA (US Energy Information Administration) raising its Brent crude forecast to $105/barrel for Q4 2026 — strongly bearish at -0.55. Today also marks the third anniversary of the October 7 Hamas attack, keeping Middle East sentiment raw; any Strait of Hormuz disruption would hit India's crude import bill directly.
Currency and commodity impact. The rupee slipped 10 paise to 96.45/USD ahead of the RBI decision, signalling macro stress even before the hike landed — moderately bearish at -0.50. The EIA's $105/barrel Brent forecast is the bigger concern: India imports roughly 85% of its crude, so sustained high prices widen the current account deficit (the gap between what India earns and spends in foreign exchange) and keep inflation elevated.
India regulatory stance. The RBI's 25 bps hike to 5.50% is the dominant regulatory event of the session, scoring moderately bearish at -0.45. Governor Malhotra's statement that the focus is squarely on bringing headline inflation back to the 4% target — with only hikes or pauses ahead, no cuts — removes a key market support that investors had been pricing in for late 2026.
Earnings momentum and corporate health. This is the session's lone bright spot, and it is a genuine one — mildly bullish at +0.45. Motilal Oswal projects Nifty 50 Q2 earnings growth at 27% year-on-year, the highest in 17 quarters. TCS (Tata Consultancy Services) Q2 results are imminent with 13% YoY revenue growth expected. Trent posted Q2 revenue growth of 23% YoY, and Kanohar Electricals doubled its revenue to ₹137 crore (₹1.37 billion). This earnings wave is the primary reason the market has not broken down further.
Sectors in focus
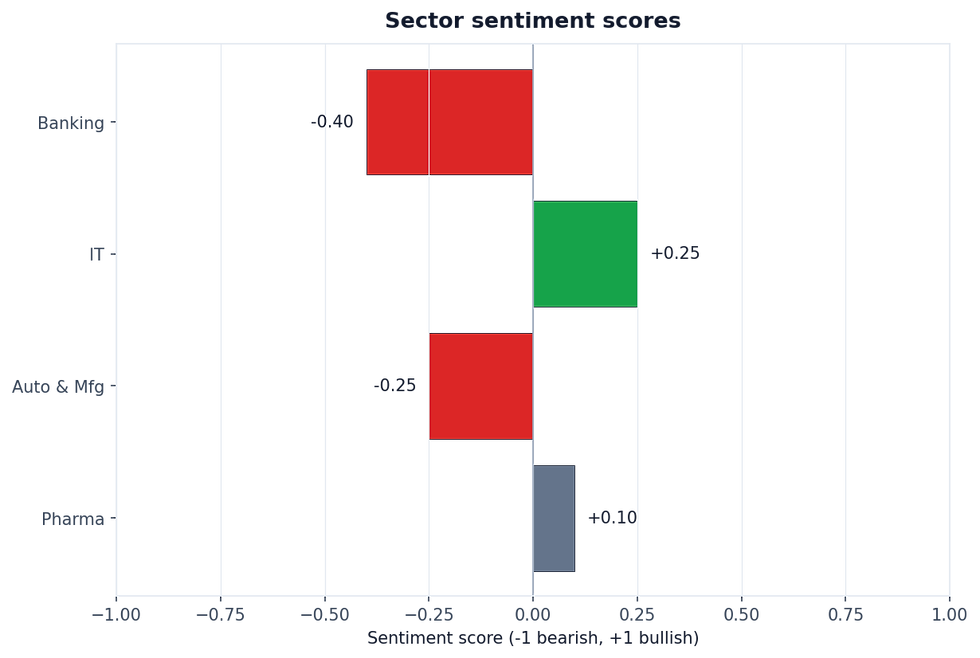
Banking. Mildly bearish at -0.40 — the RBI hike compresses NIMs (net interest margins, the difference between what banks earn on loans and pay on deposits) in the near term, and HDFC Bank is already down roughly 15% over the past three months. Interestingly, bank stocks briefly traded higher right after the hike announcement, suggesting some of the move was already priced in.
IT. Cautiously bullish at +0.25 — TCS Q2 results expected later today are the focal point, with analysts projecting 13% YoY revenue growth and healthy margin expansion. US software stocks hitting 2026 highs on AI (artificial intelligence) adoption tailwinds provides a supportive global backdrop, though IDBI Capital flags that broader IT earnings may remain subdued.
Auto & Manufacturing. Mildly bearish at -0.25 — the rate hike directly raises auto loan EMIs (equated monthly instalments), which can soften near-term vehicle demand. Manufacturing faces a separate squeeze: crude at $105/barrel pushes up input costs across the board. Titan led sectoral declines on the RBI decision, reflecting rate sensitivity across consumer discretionary names.
Pharma. Marginally bullish at +0.10, though with low confidence — there are no major USFDA (US Food and Drug Administration) actions or pharma-specific earnings in today's session. The sector's defensive characteristics may attract some rotation as investors seek shelter from rate-sensitive sectors, but the move, if any, is likely to be modest.
Global and macro backdrop
The global backdrop is adding pressure rather than relief today. The DXY (US Dollar Index, which measures the dollar against a basket of major currencies) is strengthening ahead of tonight's FOMC minutes release, which directly pressures the rupee. European markets are dealing with rising yields and energy prices — the ECB (European Central Bank) maintained its hawkish inflation-targeting stance at its September 10 meeting — creating a risk-off tone that spills into emerging markets like India.
On FII (Foreign Institutional Investor) and DII (Domestic Institutional Investor) flows, no official intraday data is available yet. However, the combination of a hawkish RBI, a weakening rupee, and Nifty down 13% year-to-date creates a difficult risk-reward calculation for foreign investors. DIIs, who tend to buy on dips, may be providing the floor that has prevented a sharper afternoon slide. China's signal is marginally positive at +0.05, but carries very low confidence and is not a meaningful driver today.
Gold fell ₹1,500 per 10 grams and silver dropped ₹1,600 per kilogram ahead of the FOMC minutes — an unusual move that suggests some investors are liquidating safe-haven positions, possibly to cover losses elsewhere or to await clearer Fed direction.
Risks to watch
FOMC minutes surprise: If the minutes reveal a more hawkish Fed than expected, the DXY could spike further, putting additional pressure on the rupee and triggering FII outflows from Indian equities.
Crude oil headlines: Any fresh escalation in the Iran war or a reported Strait of Hormuz incident could push Brent above $105/barrel intraday, worsening India's macro outlook instantly.
Nifty technical levels: With the index already down 13% year-to-date, a further afternoon leg down could trigger stop-loss selling (automatic sell orders placed below a price level to limit losses) and amplify the move.
TCS Q2 result timing: If TCS numbers land before market close and disappoint versus the 13% growth consensus, IT — currently the market's only sectoral cushion — could turn negative, removing the last meaningful support.
What this means for the rest of today's session
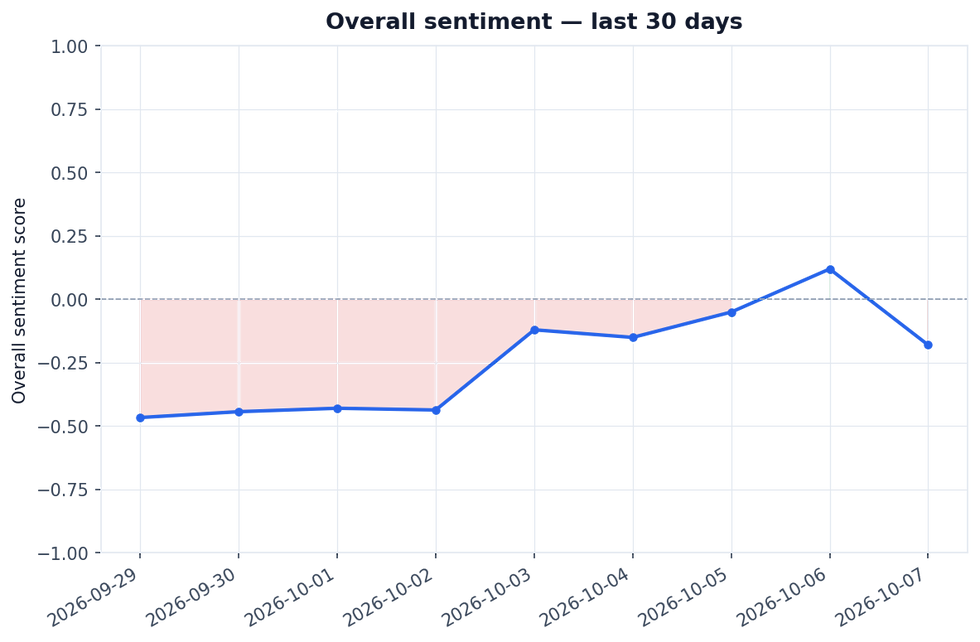
The market is in a fragile equilibrium at midday: the RBI shock has been absorbed but not forgotten, and the earnings tailwind is real but not powerful enough to flip overall sentiment positive. The next 2.5 hours hinge on two external triggers — FOMC minutes and any fresh geopolitical headline from the Middle East. If both stay quiet, the session could close with losses trimmed modestly from current levels, supported by earnings optimism. If either trigger fires, expect VIX (the volatility index, which measures expected market swings) to spike and the Sensex to test fresh intraday lows. Staying informed and avoiding reactive decisions into the close is the prudent approach for today.
How to read this
What this sentiment is measuring. We score 16 distinct dimensions of market sentiment, covering broad market direction, key sectors (banking, IT, auto and manufacturing, pharma), global cues, FII / DII flows, currency and commodities, regulatory stance across India and major foreign jurisdictions, and risk indicators. Each dimension is given a score from −1 (strongly bearish) to +1 (strongly bullish), paired with a 0 to 1 confidence weight that reflects how much supporting evidence the model found. The overall score shown in the dial is a confidence-weighted blend of all dimensions on the same −1 to +1 scale.
What data is used. The analysis draws on Indian and global financial news, regulatory and policy feeds from India as well as major foreign jurisdictions, and market news from global exchanges. News items are filtered for freshness and relevance before being scored, so the picture reflects what the market is reading and reacting to right now.
Limitations. This article is not investment advice and not a recommendation to buy, sell, or hold any security. The output is best treated as a structured attribute set — useful as one input among many when building your own prediction models or sense-checking your own view, not as a forecast on its own.


Comments